Quick answer: Queensland home warranty insurance is compulsory for residential building work worth more than $3,300. The builder pays the premium to the QBCC before work starts, and you pay for it through the contract price. Standard cover is up to $200,000 for non-completion and defects, or $300,000 with optional additional cover. Structural defects are covered for 6 years and 6 months. Non-structural defects must be noticed within 6 months of the work being substantially complete. Real Estate Investors Network (REIN), a buyer-only house and land advocate, checks house and land packages before you sign: the land and build price, the inclusions and who is paid from the price.
In this guide (7 sections)
Been shown a house and land package? Run the numbers in 60 seconds.
Free calculator: land and build split, yield, weekly cost and what to check before you sign.
Read this before you sign
- Non-completion cover only applies to fixed-price contracts, and it doesn’t apply if you are building 3 or more homes.
- Accommodation cover is for owner-occupiers only. A rented investment property does not qualify.
- Driveways, fences, landscaping, air conditioning and hot water systems are not covered by the scheme.
Already been shown a house and land package? Get My Package Checked before you sign.
Most house and land buyers in Queensland never look at their home warranty cover until something goes wrong. By then the time limits may have run. For an investor the gaps are bigger than for an owner-occupier, because some parts of the scheme were written with people living in the home in mind.
This guide covers what the Queensland Home Warranty Scheme pays for, the limits, the deadlines, and the parts of a typical house and land package it does not touch. Every fact below links to its source.
What is home warranty insurance in Queensland?
The Queensland Home Warranty Scheme is run by the QBCC. Insurance under the scheme is compulsory for all residential construction work valued at more than $3,300, including materials, labour and GST. The licensed contractor pays the premium to the QBCC before work begins, and the cost is built into your contract price.
It covers you if something goes wrong during or after the build: non-completion, defective work, and subsidence or settlement. It applies to fixed-price and cost-plus residential contracts carried out by a licensed contractor.
In a house and land package, the scheme covers the building contract. It is insurance on construction work, so it does nothing for the land contract, the land price or a delayed title.
What it covers, and the limits
| Situation | Standard cover | With optional additional cover |
|---|---|---|
| Before completion: non-completion, defects, vandalism, theft | $200,000 | $300,000 |
| Before completion: fire or storm (non-completion claim must be approved) | $200,000 | $300,000 |
| After completion: defects | $200,000 | $300,000 |
| Accommodation, removal and storage (inside the limits above) | $5,000 | $10,000 |
| Duplex, per unit, before completion | $100,000 | $150,000 |
| Duplex, per unit, after completion (defects) | $200,000 | $300,000 |
Source: QBCC, Maximum home warranty entitlements.
Note the duplex row. If you are buying a dual-key or duplex package, the cover for each unit before completion is half the standard amount. Check whether that is enough to finish your build if the builder stops.
The QBCC also lists what the scheme does not cover: driveways, paths, fences, air conditioning, hot water systems, security doors and landscaping, buildings over three storeys (not counting one storey used mainly as a car park), and commercial buildings. Many of those items are exactly the “turnkey extras” packages are sold on. If they are defective, the scheme will not pay for them.
The time limits
Cover lasts 6 years and 6 months from the earliest of the date the premium is paid, the date you sign the contract, or the date work starts. It can be extended where the work takes longer than 6 months to complete.
| Claim type | When you must become aware | When you must claim |
|---|---|---|
| Structural defect | Within 6 years 6 months of cover starting | Within 3 months of becoming aware |
| Non-structural defect | Within 6 months of substantial completion | Within 7 months of substantial completion |
| Non-completion | Contract must end within 2 years of signing (no work started) or of work starting | Within 3 months of the contract ending |
Source: QBCC, Time limits for cover and claims.
The 6-month window for non-structural defects is the one investors miss. A tenant moves in, reports a sticking door or cracked tiles to the property manager, and nobody tells the owner until month eight. By then that cover has gone. Ask your property manager to send you every maintenance report in the first six months, and book your own building inspector at handover. Our guide to building defects explains structural and non-structural defects in more detail.
Where the scheme helps investors, and where the risk sits
Where it helps
- Cover stays with the property. The QBCC says the insurance covers the property, so it remains if the home is sold. That can help when you sell inside the cover period.
- You can lift the limit. Optional additional cover raises the cap to $300,000. You must apply within 30 business days of entering the contract or before work starts, whichever is earlier. The fee depends on the value of the work.
Where the risk sits
- No accommodation cover for rentals. Accommodation and storage costs are paid only to owner-occupiers. If your tenant has to move out while defects are fixed, lost rent is your problem. Check what your landlord insurance covers.
- Non-completion needs a fixed-price contract. The QBCC lists a fixed-price contract as a condition of a non-completion claim. Ask which type you are signing.
- Building 3 or more homes. A person building 3 or more residences is not eligible for non-completion cover. If you are buying several packages at once, ask your solicitor how this applies to you.
- Paying too much, too early, cuts your payout. Payments can be reduced if you paid more than the maximum deposit allowed by law, or paid for work ahead of schedule. For domestic building contracts of $20,000 or more, the maximum deposit is generally 5% (QBCC).
- Underpriced builds. Payouts can also be reduced where the value of the work exceeds the contract price by more than 30%. A build price that looks too cheap can come back to bite you here.
- Unlicensed contractor, no cover. The scheme requires a licensed contractor. Check the builder on the QBCC licence search before you sign.
Questions to ask before you sign
- Is this a fixed-price contract?
- What is the builder’s QBCC licence number, and does the licence search match the company on the contract?
- When will the home warranty premium be paid, and will I receive the Notice of Cover?
- Is the deposit 5% or less? If not, which exception applies?
- Do the progress payments match completed stages and my lender’s schedule?
- Which items in the inclusions list sit outside the scheme (driveway, fencing, landscaping, air conditioning, hot water)?
- Should I take out optional additional cover, and what is the deadline on this contract?
The QBCC says you should receive a Notice of Cover by email once the contractor takes out the insurance. If you don’t get one, contact the builder. They may have entered their own email address by mistake.
How REIN Can Help With Home Warranty and Your Build Contract
- We read the building contract with you: contract type, deposit, payment stages and what sits outside the warranty.
- We check the builder’s licence and that cover is in place before you pay a progress claim.
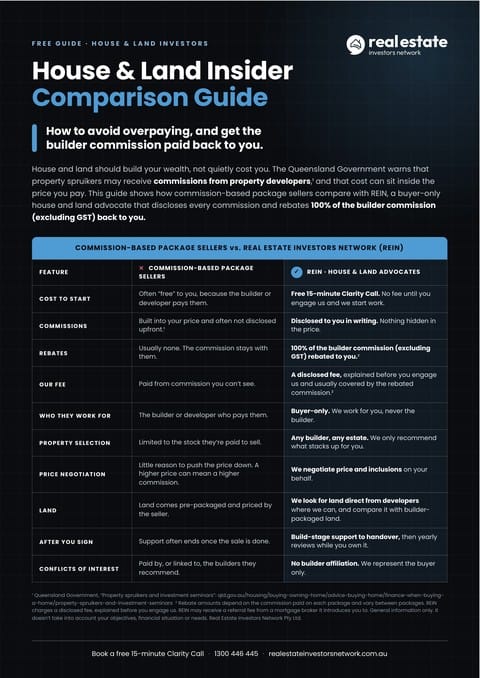
- Book a free 15-Minute Clarity Call and we’ll explain how we check the price, the commission and the contract. Any builder commission is disclosed in writing and rebated 100% to you (excluding GST).
- A disclosed fee, and 100% of builder commission (excluding GST) rebated to you.
Start with a free 15-Minute Clarity Call.
Common Questions About Home Warranty Insurance in QLD
Is home warranty insurance compulsory in Queensland?
Yes, for residential construction work valued at more than $3,300, including materials, labour and GST. The licensed contractor must pay the premium to the QBCC before work starts. You pay for it through the contract price, so check the contract shows it.
How much does QBCC home warranty insurance pay?
Standard cover is up to $200,000 for non-completion and defects before completion, and up to $200,000 for defects after completion. Optional additional cover raises each limit to $300,000. For duplexes, cover before completion is $100,000 per unit, or $150,000 with optional cover.
How long does home warranty insurance last in QLD?
Cover lasts 6 years and 6 months, and can be extended where the work takes more than 6 months. Structural defects can be claimed within that period. Non-structural defects must be noticed within 6 months of substantial completion and claimed within 7 months.
Does home warranty insurance cover an investment property?
The scheme covers residential construction work, and the QBCC’s limits above apply to it. The gap for investors is accommodation cover: only owner-occupiers can claim accommodation and storage costs. If your property is tenanted, the scheme will not pay for lost rent while repairs are done.
Does the cover transfer if I sell?
Yes. The QBCC says the insurance covers the property, so it remains if the home is sold within the cover period. Buyers can search whether cover is attached to a property on the QBCC website.
What is not covered by QBCC home warranty insurance?
The QBCC lists driveways, paths, fences, air conditioning, hot water systems, security doors and landscaping as not covered. Buildings over three storeys (excluding a car park level) and commercial buildings are also outside the scheme.
REIN is a buyers advocate for investors buying new house and land. We work only for the buyer. Are you comparing packages right now? Send us the one you’re looking at before you sign, or read more on the REIN blog.
More guides
- Building defects: what investors should know
- House and land package deposits
- Construction loans for house and land
- Pre-purchase building inspections
- What is a turnkey property?
This is general information, not legal, tax or financial advice. Speak to a Queensland property solicitor about your contract before you sign.
Written by Tom Ashby for REIN. Fact-checked against the sources below. Last updated 3 November 2026.
Important disclaimer: This article is general information only, compiled from publicly available sources on the internet. We believe it was accurate at the date of publication, but details change and errors can occur. It is not legal, tax, financial or credit advice and does not take your circumstances into account. Before you rely on anything here, confirm the facts directly with the QBCC or the government agency concerned, and speak to your accountant, solicitor or licensed adviser. Ratings, reviews and opinions quoted belong to their authors. REIN accepts no liability for decisions made on the basis of this article. To report an error, call 1300 446 445. A REIN service fee applies to our services, and where REIN receives a builder or developer commission in connection with a client’s purchase, it discloses and rebates 100% (excluding GST) of that commission to the client under its written service agreement.
Sources
- QBCC: What is home warranty insurance, accessed 3 November 2026
- QBCC: Maximum home warranty entitlements, accessed 3 November 2026
- QBCC: Time limits for cover and claims, accessed 3 November 2026
- QBCC: Home warranty for non-completion claims, accessed 3 November 2026
- QBCC: Understanding the Queensland Home Warranty Scheme: a guide for property owners, accessed 3 November 2026
- QBCC: Take out optional additional cover, accessed 3 November 2026
- QBCC: Understanding deposits and progress payments, accessed 3 November 2026
More buying guides