Quick answer: To stress-test a house and land investment, run the numbers again assuming interest rates rise, the home sits empty for a few weeks, the rent comes in lower than quoted, and the bank values it below the contract price. If you can still hold the property comfortably in that worse case, the deal is far safer. Banks already test borrowers at 3 percentage points above the loan rate, and the Reserve Bank has lifted the cash rate twice since September 2026, to 4.85%. Real Estate Investors Network (REIN), a buyer-only house and land advocate, runs these checks on a package before you sign.
In this guide (10 sections)
- Why Stress-Testing Matters Right Now
- The Worked Example
- Test 1: Interest Rates Rise by 3 Percentage Points
- Test 2: The Home Sits Empty for a Month
- Test 3: The Rent Comes In Lower Than Quoted
- Test 4: The Bank Values It Below the Contract Price
- Putting It Together: The Worse Case
- Five Questions to Ask Before You Sign
- How REIN Can Help
- Common Questions About Stress-Testing a Property Investment
Been shown a house and land package? Run the numbers in 60 seconds.
Free calculator: land and build split, yield, weekly cost and what to check before you sign.
Most package brochures show one set of numbers: today’s interest rate, a full year of rent at the quoted figure, and a price that assumes the home is worth what you pay. Real life rarely lines up that neatly. A stress test asks a simple question: if a few things go wrong at once, can you still hold the property without being forced to sell?
Every fact below links to its source. The worked example uses round figures we’ve chosen to show the method. They are not a forecast.
Why Stress-Testing Matters Right Now
The Reserve Bank of Australia raised the cash rate target by 0.25 percentage points on 30 September 2026 and again on 4 November 2026, taking it from 4.35% to 4.85% (RBA, cash rate target). Anyone who bought on numbers that only worked at the old rate is now testing those numbers for real.
Banks build in a margin of safety too. APRA, the banking regulator, requires lenders to check that new borrowers could still afford their repayments at an interest rate at least 3 percentage points above their loan rate, and kept that buffer in place in May 2026 (APRA, 28 May 2026). If the bank tests your finances that way, it makes sense to test the property that way as well.
Moneysmart lists the main risks of investing in property, including rental income that doesn’t cover the mortgage and other costs, higher repayments when rates rise, vacancy, and a fall in value that leaves you owing more than the property is worth (Moneysmart). A stress test puts a dollar figure on each one.
The Worked Example
To keep it simple, we’ll use one example package and change one thing at a time. These figures are assumptions for illustration only:
- Package price: $650,000
- Loan: $520,000 (80% of the price), interest only
- Quoted rent: $600 a week
- Starting interest rate: 6.5%
At those numbers, the rent is $31,200 a year and the interest is $33,800 a year. Before any other costs, you’re about $2,600 a year short, or around $50 a week. That’s the brochure case.
Test 1: Interest Rates Rise by 3 Percentage Points
Use the same buffer the banks use. At 9.5% instead of 6.5%, interest on a $520,000 loan rises from $33,800 to $49,400 a year. That’s $15,600 a year more, or about $300 a week.
Ask yourself whether your income could cover that for a few years without strain. If the answer is no, the property may be too big a stretch, however good the brochure looks.
Test 2: The Home Sits Empty for a Month
New homes often take time to find a first tenant, and every change of tenant can leave a gap. Allow for at least four weeks without rent in the first year. At $600 a week, four empty weeks cut your rent from $31,200 to $28,800.
Check how many other new homes are being finished nearby at the same time. If a whole stage is completing together, you may be competing with dozens of other landlords for the same tenants. Here’s how to spot an oversupplied suburb.
Test 3: The Rent Comes In Lower Than Quoted
A quoted rent on a package is an estimate, not a lease. Compare it with the median rent for the same size home in the suburb. In some areas the gap is large: in our Melton guide, for example, REIV’s four-bedroom median rents were $460 to $480 a week.
Test the numbers with the rent 10% lower than quoted. In our example, $540 a week for 48 weeks brings in $25,920 a year.
Test 4: The Bank Values It Below the Contract Price
If the bank’s valuation comes in under what you agreed to pay, it lends against the lower figure. Say the $650,000 package is valued 5% lower, at $617,500. At 80% of that value, the bank lends $494,000, not $520,000. You’d need to find about $26,000 more in cash, or pay lenders mortgage insurance, to settle.
This risk is higher when a package is priced at or above what similar homes are selling for. Here are six checks to see if your package is overpriced.
Putting It Together: The Worse Case
Now combine the tests: interest at 9.5%, four weeks of vacancy and rent 10% below the quote.
| Measure | Brochure case | Stress case |
|---|---|---|
| Interest rate | 6.5% | 9.5% |
| Weekly rent | $600 | $540 |
| Weeks rented | 52 | 48 |
| Rent for the year | $31,200 | $25,920 |
| Interest for the year | $33,800 | $49,400 |
| Shortfall before other costs | $2,600 a year (about $50 a week) | $23,480 a year (about $450 a week) |
That shortfall is before council rates, insurance, property management, maintenance and any other holding costs. Here’s what a house and land investment really costs to hold. Tax deductions may reduce the after-tax cost, but they don’t put cash in your account each week, so speak to your accountant about your own situation.
The point isn’t that this will happen. It’s that you should know the number before you sign, and be confident you could carry it for a while if it did.
Want this run on a package you’ve been shown? Get My Package Checked before you sign.
Five Questions to Ask Before You Sign
- What’s my weekly shortfall at a rate 3 percentage points higher? Work it out on your actual loan, not the brochure.
- Is the quoted rent backed by a written rental appraisal? Compare it with the suburb median for the same size home.
- How many other homes are being finished nearby at the same time? Ask the estate for stage release and completion dates.
- How does the price compare with recent sales of similar new homes? That’s what a valuer will look at.
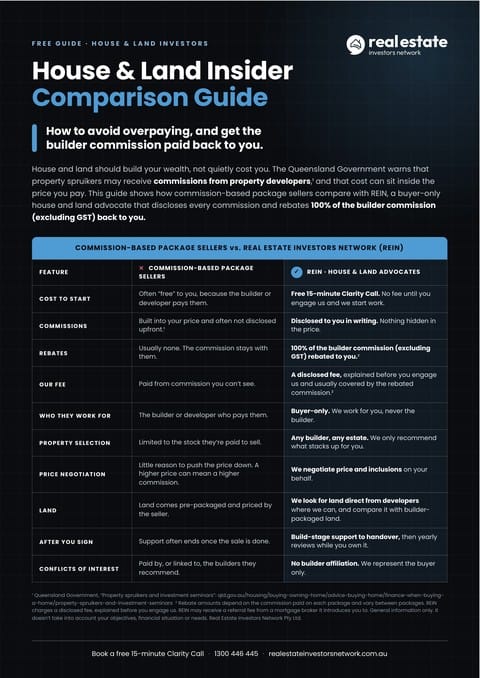
- Who’s paid from the price? If anyone introduced you to the package, ask in writing whether they’re paid a commission, by whom, and how much. Here’s how hidden commissions in house and land packages work.
How REIN Can Help
You don’t have to work all of this out on your own. REIN acts only for the buyer. Before you sign, we’ll check the package for you:
- Is the price competitive? We compare the land and build price with what similar property is selling for in the area.
- Do the numbers hold up? We check the quoted rent against the market and run the cash flow at higher rates and with vacancy.
- Is there a commission in the price? We ask in writing who’s being paid and how much, so you know before you sign.
How we’re paid: a disclosed fee, and 100% of builder commission (excluding GST) rebated to you.
Common Questions About Stress-Testing a Property Investment
What does it mean to stress-test an investment property?
It means recalculating the numbers under worse conditions, such as higher interest rates, a period without a tenant, lower rent and a lower valuation, to check you could still hold the property.
How much should I add to the interest rate?
A common starting point is the 3 percentage point buffer APRA requires banks to use when they assess new borrowers.
How many weeks of vacancy should I allow for?
There’s no fixed rule. Allowing for at least four weeks in the first year is a sensible test for a new home, and more if many homes nearby are finishing at the same time.
What happens if the bank values my package lower than I paid?
The bank lends against its valuation, so you may need to put in more cash or pay lenders mortgage insurance to settle.
Can REIN stress-test a package for me?
Yes. Book a free 15-Minute Clarity Call and we’ll check the price, the rent, the cash flow and any commission built into the package.
Written by Tom Ashby for REIN. Fact-checked against the sources below. Last updated 20 November 2026.
Important disclaimer: This article is general information only, compiled from publicly available sources on the internet. We believe it was accurate at the date of publication, but details change and errors can occur. It is not legal, tax, financial or credit advice and does not take your circumstances into account. The worked example uses assumed figures for illustration only and is not a forecast. Before you rely on anything here, confirm the facts directly with your lender, the builder or the government agency concerned, and speak to your accountant, solicitor or licensed adviser. REIN accepts no liability for decisions made on the basis of this article. To report an error, call 1300 446 445.
Sources
- Reserve Bank of Australia: Cash rate target, accessed 20 November 2026
- APRA: APRA maintains current macroprudential policy settings in highly uncertain environment, 28 May 2026, accessed 20 November 2026
- APRA: System Risk Outlook, May 2026, accessed 20 November 2026
- Moneysmart: Buying an investment property (updated 29 September 2026), accessed 20 November 2026
- REIV: Melton South suburb insights, accessed 19 November 2026
More buying guides